


As early as 2019, I wrote in the South China Morning Post suggesting that China and the United States might consider a “reciprocal zero-tariff” approach as a possible solution. Some might find this idea surprising, since the tariff war launched by the United States—starting April 2 of that year—against both China and the rest of the world was carried out under the banner of “reciprocal tariffs.” What I proposed back in 2019, however, was a “reciprocal zero-tariff war.” Let me first explain the general concept behind this idea.
According to Chinese customs statistics, in 2024 China imported about USD 163.6 billion worth of goods from the United States and exported about USD 524.7 billion to the U.S., producing a trade surplus of USD 361 billion. The ratio of U.S. exports to China versus Chinese exports to the U.S. is roughly 1 to 3, indicating a significant trade imbalance. For simplicity, let’s assume China imports USD 170 billion from the U.S. and exports USD 510 billion to the U.S. Could China and the U.S., through joint efforts, find a way to move toward balanced trade? The answer is yes.
What is President Trump’s current strategy? He is working on subtraction. Whose subtraction? He wants to cut down China’s exports to the United States—say, from USD 510 billion—by taking strong measures to slash the figure, even by half or more, down to USD 170 billion, thereby achieving “reciprocity” in exports, with USD 170 billion going each way.
Of course, Trump has many other objectives with his “subtraction,” but to simplify: his administration is trying to reduce China’s exports to the U.S., while at the same time aiming to do addition on the American side—boosting U.S. exports to China. And what does he want to sell to us? Crude oil, natural gas, grain, and other agricultural and related products.
Must we passively discuss with the U.S. only how to reduce our exports to them? That is clearly not the best option. Therefore, I believe that in negotiations with the United States, we should consider whether “addition” could be used to improve the China–U.S. trade relationship, rather than focusing solely on how to cut Chinese exports to the U.S.
Specifically, could we create an opportunity for the U.S. to go back home, search through what they have, and see what more they can sell to China—products that are high-quality, reasonably priced, and in demand in the Chinese market? This would form a fair and reasonable pattern of trade, encouraging the U.S. to focus on addition, finding more goods to sell to China, while China could make corresponding adjustments based on actual conditions.
Some say that China’s market is of a fixed size, so buying more from the U.S. would inevitably mean buying less from other countries. This is partly true, but it overlooks one thing: China’s market is so large that one of its defining characteristics is sheer volume. From this perspective, China retains strong bargaining power, since the price for a single kilogram and the price for a one-thousand-ton order are clearly not the same.
At present, nearly 100% of the products China imports from the United States are used within China’s domestic industrial supply chain. Some goods, of course, are processed and then sold back to the U.S. as finished products. We could consider using our vast market size to increase imports from the U.S., with part of those imports serving China’s domestic market, and another portion being re-exported to other countries as an intermediary trader.
Back in 2017, during President Trump’s first term, when he visited China in the fall, China signed large contracts to purchase crude oil and natural gas from the U.S. It takes several years for such agreements to translate into actual deliveries. So, when the Russia–Ukraine conflict broke out in 2022 and Europe faced severe energy shortages, China happened to begin receiving some of the liquefied natural gas shipments agreed upon in the 2017 China–U.S. energy cooperation deals.
From my understanding, much of the liquefied natural gas purchased by China from the U.S. at that time was not shipped back to China, but—given Europe’s energy crisis—was sent directly from U.S. ports to Europe. Was this good for us? Yes. Because prices had risen several times over, and we profited. So even if China acts purely as an intermediary, as long as we time it well and control overall volume and market conditions, this role can be highly profitable.
Many major multinational corporations operate globally in exactly this way: they do not consume 100% of what they purchase but resell it to other markets. If we in China approach the China–U.S. trade relationship with a fresh perspective, we could develop new business models—expanding purchases from the U.S., with part serving China’s market and part resold to other countries. This could turn out to be a very good business.
Second, let us imagine proposing to the United States: how about achieving zero tariffs in China–U.S. trade? President Trump might initially think this is a good idea—after all, U.S. exports to China would also enjoy zero tariffs when entering the Chinese market. But once he does the math, he will quickly feel it is a losing deal. He would point out that the U.S. exports less than USD 170 billion to China that would enjoy “zero tariffs,” while China exports USD 510 billion to the U.S. tariff-free. From the American perspective, that seems like a loss, so he might refuse.
We could therefore consider another approach: take the USD 170 billion in U.S. exports to China as the base, and adjust annually according to the actual export amount—say, USD 200 billion next year, USD 250 billion the year after. In the first year, we use the previous year’s total U.S. exports to China as the baseline. This portion of goods would enjoy zero-tariff entry into the Chinese market, which would be a major benefit for the U.S. We could allow President Trump to announce that the door has been opened for American goods to enter China tariff-free—a “significant contribution” to the U.S. economy—giving him ample material to boast about his political achievements and bolster his reputation.
However, if the USD 170 billion worth of U.S. exports to China enjoy zero tariffs, while China’s USD 510 billion worth of exports to the U.S. do not, then that would be unequal treatment for China. So could we arrange it such that, since the U.S.’s USD 170 billion in exports to China enjoy zero tariffs, an equivalent USD 170 billion of Chinese exports to the U.S. would also be granted zero-tariff access to the American market?
At first, the Americans might be reluctant. But if we appeal both to reason and to their interests, the possibility of achieving reciprocal tariff exemptions of USD 170 billion each way is actually quite high.
Now, with China’s total exports to the U.S. at about USD 510 billion, how would we handle the remaining USD 340 billion in trade? For Chinese exports exceeding the USD 170 billion zero-tariff quota, the U.S. could set its own tariff policy.
Some may feel that such an arrangement is not entirely fair or reasonable. But in reality, if we can guarantee that the U.S.’s USD 170 billion in exports to China can enter tariff-free, and that an equivalent USD 170 billion in Chinese exports can also enter the U.S. tariff-free, then neither side is disadvantaged. Given that China’s total exports to the U.S. far exceed U.S. exports to China, it would be acceptable for the U.S. to have full discretion over the tariff policy for the portion exceeding that baseline.
Many people might think this approach is somewhat reasonable, though others may question whether it is too idealistic or even naïve. After all, under WTO rules, trade statistics between countries must be broken down into detailed categories—such as electronics, agricultural products, textiles, and so on—with very specific sub-classifications. China’s exports to the U.S. cover numerous categories, so simply lumping different categories together to make up a USD 170 billion quota raises the question: what about the other categories?
This leads to another important suggestion of mine: since U.S. exports to China—regardless of category—could enter the Chinese market tariff-free under the current statistical system, the U.S. side would not need to adjust its statistical methods. It could simply maintain its existing system when exporting to China.
However, for Chinese exports to the U.S., I believe it is necessary to re-examine and clearly define the statistical scope. Specifically, I propose classifying Chinese exports to the U.S. based on the ownership of the producer into three categories:
1. Products manufactured by Chinese domestic companies and exported to the U.S.;
2. Products manufactured in China by U.S.-invested companies and sold back to the U.S.;
3. Products manufactured in China by companies from other countries and regions (such as the EU, Japan, ASEAN, etc.) and exported to the U.S.
In other words, China’s exports to the U.S. should be divided into three major groups by producer identity: Chinese companies, U.S. companies operating in China, and other foreign-invested enterprises.
If both sides agree to this arrangement, the zero-tariff quota could be allocated first to products made in China by Chinese domestic companies and exported to the U.S. Our companies would likely exhaust this quota quickly. As for U.S.-invested companies, European and other foreign-invested companies producing in China and exporting to the U.S. but outside the USD 170 billion quota, their products would no longer enjoy zero tariffs and would instead be subject to whatever duties the U.S. government imposes.
So how would the U.S. impose these tariffs? First, the volume of products manufactured in China by U.S.-invested companies and exported back to the U.S. is also significant. The share varies from year to year, but in the past we had a rough “three-thirds” description: about one-third of China’s exports to the U.S. by value come from Chinese companies, another third from U.S.-invested companies in China, and the final third from companies of other countries and regions—such as Taiwan—operating in China. Of course, this ratio changes constantly, and we should base decisions on the latest analysis.
Since the USD 170 billion quota of Chinese exports to the U.S. would enjoy zero tariffs, this quota would mainly cover the first category—products made by Chinese companies. For the second and third categories, the U.S. government could impose tariffs as it sees fit.
If the U.S. government were to impose high tariffs on products made in China by U.S.-invested companies and shipped back to the U.S., the impact would be significant. The American companies I have dealt with in China are no ordinary players—they have deep connections in the U.S. and employ powerful lobbying firms. Faced with high tariffs, they would surely head to Washington, calling the White House daily to tell President Trump: “This is unfair. You grant zero tariffs to products made by Chinese companies and shipped to the U.S., but we are American companies, and you want to tax our products heavily when we sell them back to our own country. That doesn’t make sense,” and so on.
After April 2 this year, when the U.S. set tariffs on Chinese products at 145%, many American companies in China also pushed back. They went to Washington to lobby President Trump—especially in industries like electronics, where production is concentrated among U.S. companies in China—and tariffs on such products were later substantially reduced.
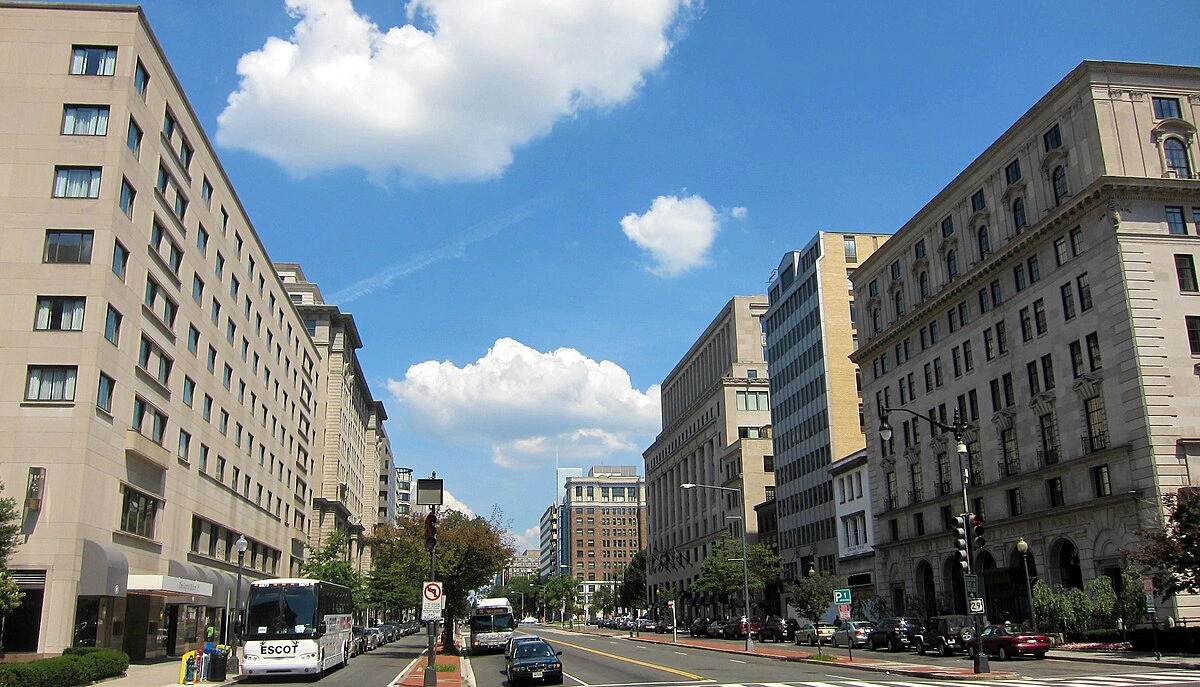 K Street—the famous hub of Washington’s lobbying firms
I have full confidence in the influence of U.S. companies operating in China. They will certainly lobby President Trump and the U.S. government vigorously to reduce or remove impending tariffs. The final tariff rates and collection methods will ultimately be the result of bargaining between the U.S. government and these American companies in China.
As for the third category—companies from countries and regions outside the U.S., such as the EU, Southeast Asia, Japan, South Korea, Australia and New Zealand products they manufacture in mainland China and export to the U.S. would be subject to whatever tariffs the U.S. decides to impose. If President Trump and the U.S. government opt for high tariffs, these countries and regions will not sit idly by—they will also lobby and negotiate with the U.S. government. Thus, before finalizing any tariff measures, the U.S. government will inevitably go through a round of bargaining with them as well.
Overall, the advantage of this arrangement is that it first ensures U.S. exports to China—roughly USD 170 billion—enter tariff-free. At the same time, Chinese exports to the U.S. in the first category—products made by Chinese companies—would enjoy a matching USD 170 billion zero-tariff quota. For products in the second and third categories, the U.S. would decide tariff rates, and in that process, many parties besides China would also have a stake and join the bargaining with Washington.
In addition, this arrangement allows us to lavish praise on President Trump, satisfying both his vanity and his desire to achieve something big. We could even frame it so that people say he is the greatest U.S. president in history—after all, President Nixon merely opened the door between China and the U.S., while President Trump opened the door for U.S. products to enter China tariff-free. For American businesses, this would be a tremendous boon—one they had not imagined in decades.
Meanwhile, China would not be at a disadvantage, because the arrangement is reciprocal: USD 170 billion for USD 170 billion. If next year U.S. exports to China rise to USD 200 billion, then it becomes 200 for 200; if they rise to USD 300 billion, it becomes 300 for 300. Each year, the quota would be recalculated, ensuring a dynamic rather than static solution.
Editor: LQQ
Note: This is a translated and edited version of the original article in Chinese:
Zhan Xiao Ting
This method of limiting zero tariff to the amount of US export to china may hopefully appeal to the US objective of reciprocal tariffs. But if reciprocal trade is only a tool president Trump uses to make America great again -MAGA, it may not fully satisfy Trump’s goal of MAGA as China will continue to grow in economic size, albeit at a somewhat tempered pace. In the end compromises have to be made and common sense must prevpail.