On July 31st, the “Regulations of the State Council on Exit and Entry Administration” was officially announced and will be implemented from September 15th, 2026. Coincidentally, just a few days ago, the Ministry of Finance and the State Taxation Administration issued new regulations on individual income tax for offshore trusts.
Recently, a series of new regulations linked to “cross-border” issues have emerged one after another, leaving people overwhelmed. New tax regulations for offshore trusts have been implemented, along with the determination of tax resident status, the CRS global financial account information exchange, and the fourth phase of the Golden Tax Project… The regulatory defense line is constantly being strengthened.
Not long ago, the China Securities Regulatory Commission (CSRC) and other departments severely investigated and dealt with the illegal conduct of cross-border securities business without approval. Coupled with the security assessment of data export, the supervision of cross-border payments, and now the new regulations on exit and entry management, it seems that a combination of measures is being formed.
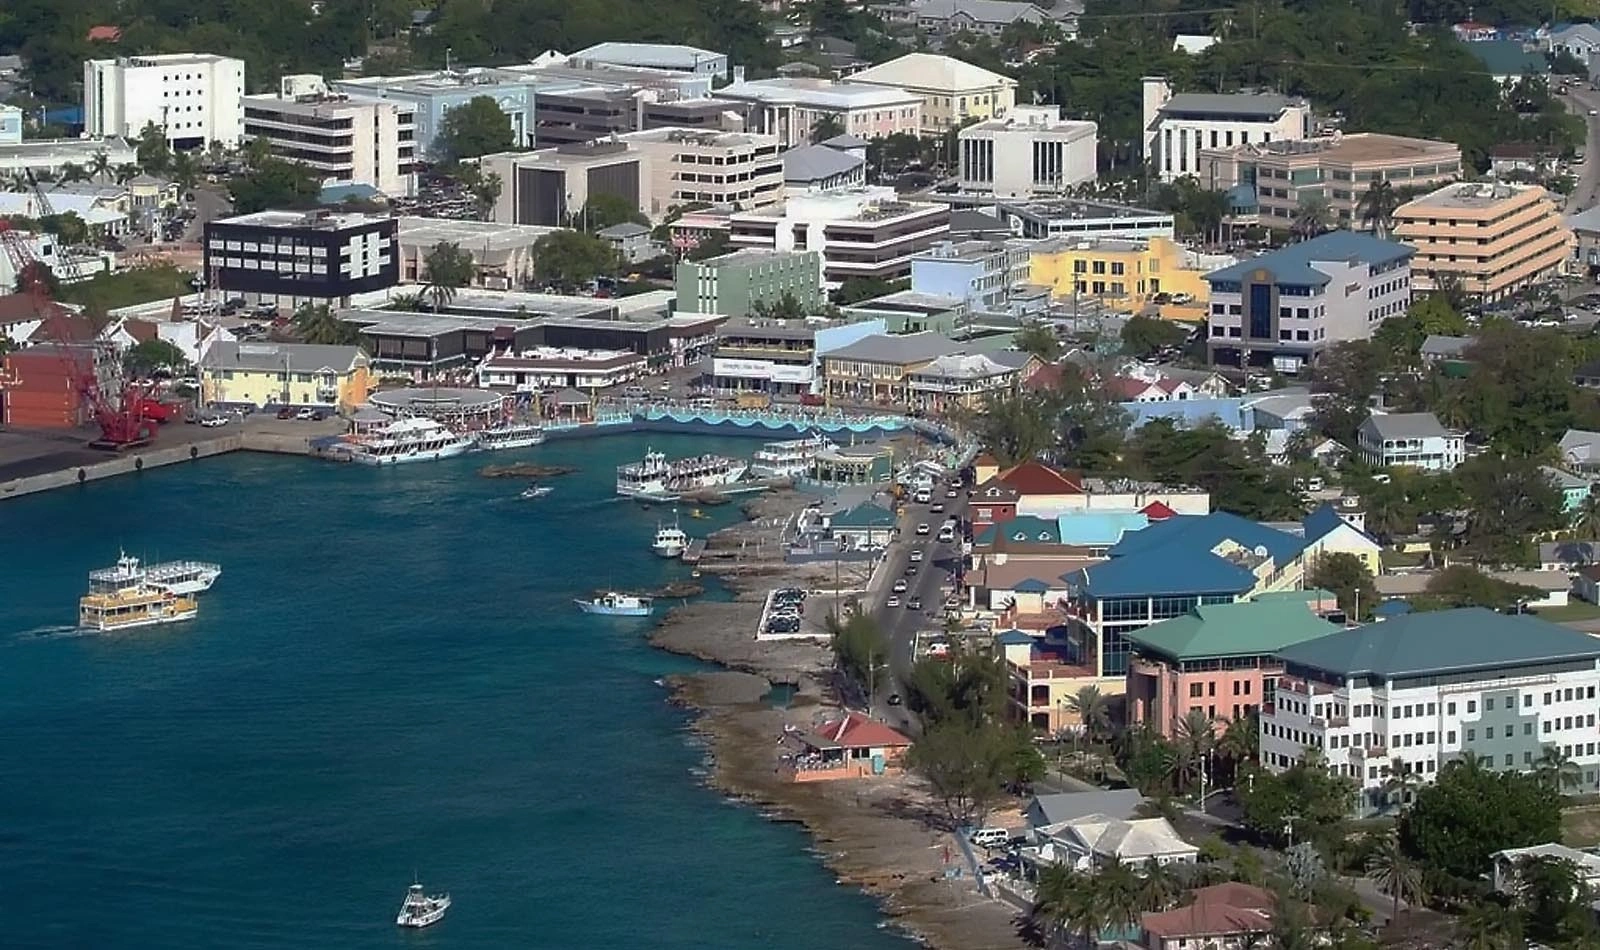 The Cayman Islands is a globally recognized offshore trust jurisdiction,where many wealthy Chinese individuals transfer their assets to shell companies registered.
Looking at any single aspect, there are considerations behind each: tax departments seek tax fairness, immigration management departments focus on entry and exit order, cyber and information departments keep an eye on data security, and foreign exchange departments keep a close watch on capital flows. Separately, they seem to be busy with their own affairs, but a clear main thread has emerged: they are all answering the same core question: what rules should be followed for future cross-border activities.
Many people’s first reaction to the word “management” is “restriction”. This intuition is actually off the mark.
Over the past few years, cross-border activities in China have long ceased to be the privilege of a select few. With hundreds of millions of cross-border trips made each year, intensive global trade and investment, and the widespread popularity of studying abroad, tourism, and family visits, cross-border activities have long become integrated into daily life. As traffic volume increases, rules and regulations naturally need to keep pace. This is akin to the situation when highways were first opened to traffic with only a few cars, where past experience sufficed; now, with millions of cars traveling side by side daily, traffic laws and regulations must become increasingly detailed.
Having understood this principle, when we look at the new regulations issued by the State Council this time, we will find that many provisions are not fabricated out of thin air, but rather a systematic sorting and integration of regulations previously scattered in various laws and administrative regulations. Essentially, they are framework documents that focus on unifying norms, rather than specifically targeting a particular group.
Is the new regulation on offshore trusts the same case? The answer is undoubtedly yes. Currently, there are two extreme interpretations of offshore trusts: one is that it is targeting the wealthy, and the other is that it is suppressing the global allocation of capital. Both views are overly one-sided. Is the new regulation on offshore trusts the same case? The answer is undoubtedly yes. Currently, there are two extreme interpretations of offshore trusts: one is that it is targeting the wealthy, and the other is that it is suppressing the global allocation of capital. Both views are overly one-sided.
Offshore trusts have been in existence for hundreds of years and are a highly mature standard tool in international wealth management. It is a common practice for founders of multinational corporations, shareholders of listed companies, or family foundations to utilize them for asset separation, inheritance, or charitable purposes. The tool itself carries no inherent sin, but the environment has changed.
Over the past two decades, capital has been flowing frantically around the world. With the help of complex offshore structures, overseas shareholdings, and trust arrangements, considerable wealth has achieved tax deferral or even long-term evasion from regulation. As global tax transparency has significantly increased, this decades-old practice has naturally reached a crossroads of change.
This is by no means a unique action in China. Over the past decade, the OECD has vigorously promoted reforms to prevent Base Erosion and Profit Shifting (BEPS), the global minimum corporate tax has been gradually implemented, and the Common Reporting Standard (CRS) information exchange has covered an increasing number of countries. Even Europe, the United States, and many traditional offshore financial centers are simultaneously tightening tax transparency.
The focus of global discussions has long shifted, and there is now a global consensus that “cross-border activities can be established on the basis of openness, transparency, and verifiability”.
Having recognized this broader context, the logic becomes completely clear when examining China’s recent series of actions. The core intention of the policy is not simply and crudely to restrict who can go out or who can carry money, but to provide a clear plan: today’s China has deeply integrated into the world, so how should the cross-border order be reshaped in the coming decades? The new regulations on offshore trusts and exit-entry administration are precisely crucial pieces in this new puzzle.
Setting aside the macro perspective and focusing on the lives of ordinary people, will these new regulations bring about changes? Upon reading the full text of the Regulations, it is not difficult to find that the basic framework of Chinese citizens leaving the country legally and foreigners entering the country legally remains intact, and there are no new general restrictions added. What it does is to clarify the procedures for document processing, port inspection, stay and residence, emphasizing law-based management and protection of legitimate rights and interests.
This continues the prevailing style of domestic legislation in recent years. Just like the successive introduction of the Data Security Law, the Personal Information Protection Law, and the Customs Law, matters that were previously handled by departmental regulations or even administrative practices are now being comprehensively brought into the clear and open legal framework. For the vast majority of law-abiding ordinary people, legal tourism, studying abroad, and business activities remain as usual, and the procedures are even more worry-free due to transparency.
Those most affected are precisely those who were accustomed to engaging in gray operations such as “exploiting loopholes”. For example, using institutional gaps in different jurisdictions to build multi-layered offshore structures, or relying on information asymmetry to keep assets hidden from regulatory oversight for extended periods. With the exchange of tax information, the integration of departmental data, and the deepening of international anti-tax avoidance cooperation, these gray areas are being rapidly compressed.
Therefore, it is not accurate to simply attribute the recent changes to “tightened regulation”. A more appropriate understanding is that the rules are moving towards unification. In the past, cross-border relied on exploiting “differences” among countries, while in the future, it will rely on adapting to “converging” rules.
Faced with this shift, for enterprises, the future “going global” competition is no longer just about market competition, but also about a compliance endurance race. Whether tax planning is legal, whether data export is compliant, and whether it can meet both internal and external regulations will directly determine the survival space of enterprises.
For high-net-worth families, the demand for global allocation of wealth remains reasonable, and tools such as family trusts will not disappear, but this must be based on truthful declaration, tax compliance, and information transparency.
For the general public, a system where cross-border activities are not affected by laws and responsibilities are clearer is in itself a powerful guarantee.
From a broader perspective, over the decades of reform and opening up, we have continuously lowered thresholds and actively integrated into the global community, which has been the key to our economic takeoff. Nowadays, as the world’s second-largest economy and major trading nation in goods, the volume of cross-border activities in China has grown significantly. Cross-border activities have become a daily routine for hundreds of millions of people, and a mature, stable, and predictable rule system is precisely the indispensable cornerstone for high-level openness.
The open door will not be closed due to the improvement of rules. Whether it’s the new regulations on offshore trust taxation or the regulations on entry and exit management, they all send the same signal: China’s cross-border governance is entering a new stage, upgrading from simply “facilitating mobility” to “emphasizing both facilitating mobility and rule governance”. The future world remains vast, and the opportunities for everyone to cross national borders will not decrease. However, every step we take will be more solid and transparent.
Editor: Gu Shengze